Passer au contenu principal
1
Tél : +33 (0)1 58 56 10 00
Fax : +33 (0)1 58 56 10 01
www.octo.com© OCTO 2015
50, avenue des Champs-Elysées
75008 Paris - FRANCE
FinTech Day
25 mars 2015 – Paris
2
3
Le « Why » d’OCTO
Why OCTO
+
Demander questionnaire
4
Sur le podium Best Workplace 2015!
5
Banque Digitale & FinTech : le Livre Blanc
6
Tél : +33 (0)1 58 56 10 00
Fax : +33 (0)1 58 56 10 01
www.octo.com© OCTO 2015
50, avenue des Champs-Elysées
75008 Paris - FRANCE
Banques & FinTechs :
Concurrents ou partenaires ?
Sylvain FAGNENT Stephen PÉRIN
FinTech Day – 25 mars 2015, Paris
7
FinTech : contraction de « Finance » et
« Technologie ».
Entreprise offrant des services financiers
s’appuyant sur la technologie.
Définition rapide d’une FinTech…
“
”
8
…mais encore ?!
“
”
FinTech are recreating a new world
supporting, displacing and disintermediating
the old world finance with technology.
Fintech is a new market.
It is 21st century finance.
Chris Skinner
Bloggeur, The Finanser
9
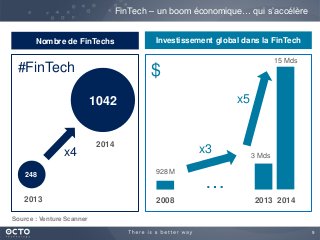
FinTech – un boom économique… qui s’accélère
248
1042
2013
2014
Source : Venture Scanner
Nombre de FinTechs
x4
#FinTech
2008 2013 2014
…
3 Mds
928 M
Investissement global dans la FinTech
$
15 Mds
x3
x5
10
Le royaume de sa majesté en ébullition
Photo:JohnStillwell,WPAPool/GettyImages
11
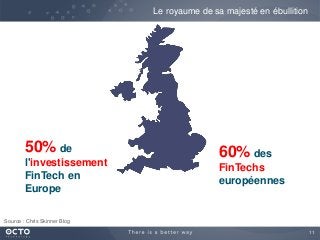
Le royaume de sa majesté en ébullition
50% de
l'investissement
FinTech en
Europe
60% des
FinTechs
européennes
Source : Chris Skinner Blog
12
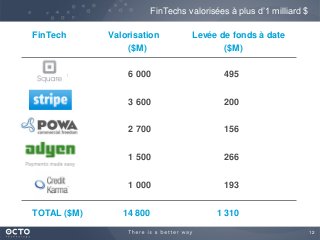
FinTech Valorisation Levée de fonds à date
($M) ($M)
1. Square 6 000 495
2. Stripe 3 600 200
2 700 156
1 500 266
1 000 193
TOTAL ($M) 14 800 1 310
FinTechs valorisées à plus d’1 milliard $
13
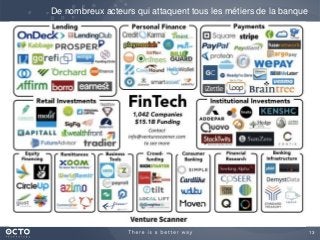
De nombreux acteurs qui attaquent tous les métiers de la banque
14
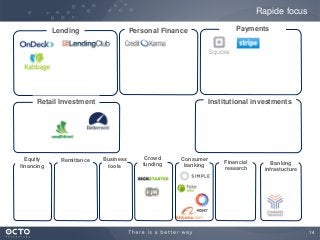
Rapide focus
Lending Personal Finance Payments
Institutional investmentsRetail Investment
Equity
financing
Remittance Business
tools
Crowd
funding Financial
research
Banking
infrastucture
Consumer
banking
15
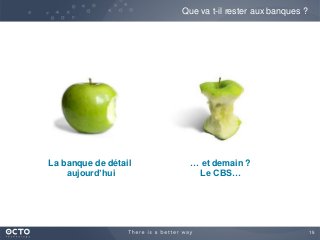
Que va t-il rester aux banques ?
La banque de détail
aujourd’hui
… et demain ?
Le CBS…
16
Va-t-on dépasser
l’affrontement ?
Au-delà du choc frontal
“
”
17
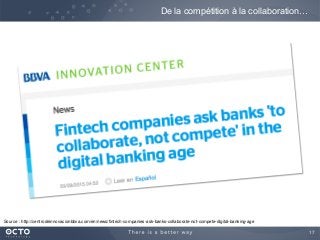
De la compétition à la collaboration…
Source : http://centrodeinnovacionbbva.com/en/news/fintech-companies-ask-banks-collaborate-not-compete-digital-banking-age
18
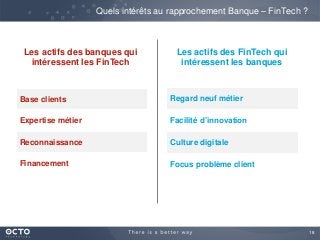
Quels intérêts au rapprochement Banque – FinTech ?
Base clients
Expertise métier
Reconnaissance
Financement
Regard neuf métier
Facilité d’innovation
Culture digitale
Focus problème client
Les actifs des FinTech qui
intéressent les banques
Les actifs des banques qui
intéressent les FinTech
19
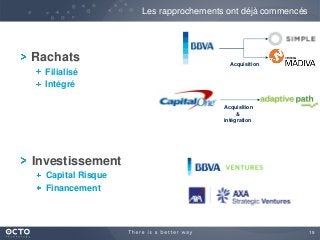
Rachats
Filialisé
Intégré
Les rapprochements ont déjà commencés
Acquisition
Acquisition
&
intégration
Investissement
Capital Risque
Financement
20
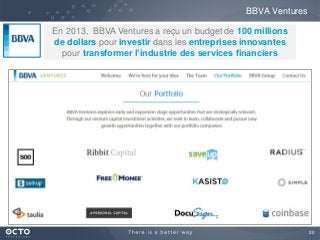
BBVA Ventures
En 2013, BBVA Ventures a reçu un budget de 100 millions
de dollars pour investir dans les entreprises innovantes
pour transformer l’industrie des services financiers
21
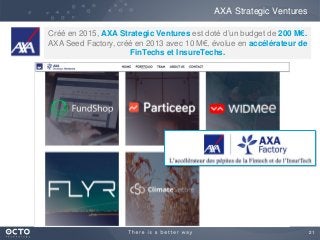
AXA Strategic Ventures
Créé en 2015, AXA Strategic Ventures est doté d’un budget de 200 M€.
AXA Seed Factory, créé en 2013 avec 10 M€, évolue en accélérateur de
FinTechs et InsureTechs.
22
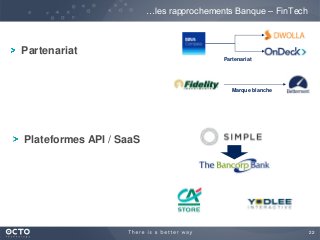
Partenariat
…les rapprochements Banque – FinTech
Partenariat
Marque blanche
Plateformes API / SaaS
23
Oui, mais…
les ADN sont-ils vraiment
compatibles ?
Est-ce que la greffe va
prendre ?
Une grande question
“
”
24
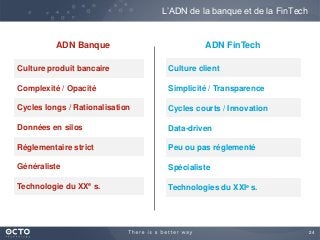
L’ADN de la banque et de la FinTech
Culture produit bancaire
Complexité / Opacité
Cycles longs / Rationalisation
Données en silos
Réglementaire strict
Généraliste
Technologie du XXe s.
ADN Banque
Culture client
Simplicité / Transparence
Cycles courts / Innovation
Data-driven
Peu ou pas réglementé
Spécialiste
Technologies du XXIe s.
ADN FinTech
25
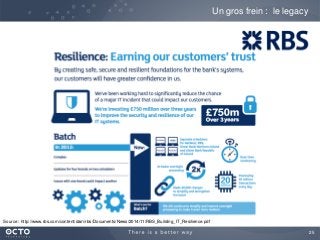
Un gros frein : le legacy
Source : http://www.rbs.com/content/dam/rbs/Documents/News/2014/11/RBS_Building_IT_Resilience.pdf
26
L’exemple de Simple
“Reinventing online banking with modern
web and mobile experiences, no surprise
fees, and great customer service”
27
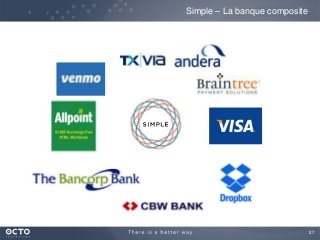
Simple – La banque composite
28
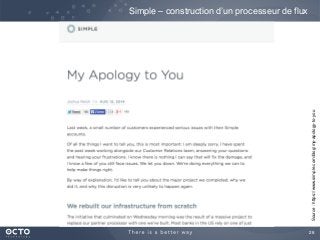
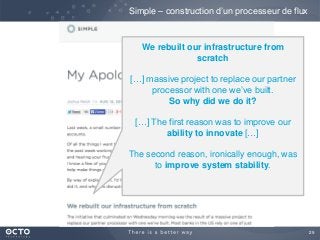
Simple – construction d’un processeur de flux
Source:https://www.simple.com/blog/my-apology-to-you
29
Simple – construction d’un processeur de flux
We rebuilt our infrastructure from
scratch
[…] massive project to replace our partner
processor with one we’ve built.
So why did we do it?
[…] The first reason was to improve our
ability to innovate […]
The second reason, ironically enough, was
to improve system stability.
30
L’exemple de Standard Treasury
31
L’exemple de Standard Treasury
32
“We are building an API banking platform,
becoming our own bank”
La vision de Standard Treasury
“We have been unimpressed with
existing bank infrastructures”
Source : http://blog.zactownsend.com/standard-treasury-as-a-startup-bank
33
Conclusion
Le rapprochement va
demander des efforts de
la part des banques.
“
”
34
Mutation spontanée
Source : http://www.craveonline.com/images/stories/2011/2011/October/Comedy%20Channel/dr-manhattan.jpg
35
Des banques avec les
gènes de la FinTech.
Mutation
“
”
36
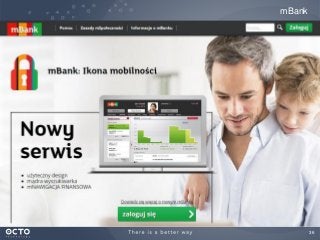
mBank
37
Fidor
38
Standard Treasury
39
La vision de Standard Treasury
“We want to be the Amazon Web Services of banking. Our wholesale
commercial banking infrastructure will be unknown to most of the public, but it
will power some of the biggest applications and companies in the world.
Becoming a bank: we must be our own regulated, deposit-taking institution in
order to build our platform and product we are planning. Our core banking
system is built using an API-first design. …. Because we started from
scratch, we built our system with security, reliability, speed, and usability.
I (Zachary Townsend, Co-Founder of Standard Treasury) care about the
potential social impact of a bank that changes the cost structure of
financial services. … not just because I might do well economically, but because
it would be one of the most powerful ways for me to help others do well
economically.
I hope to radically change the equation through our systems, allowing
many more people to have access to the financial system.”
“We want to be the Amazon Web Services
of banking”
Source : http://blog.zactownsend.com/standard-treasury-as-a-startup-bank
40
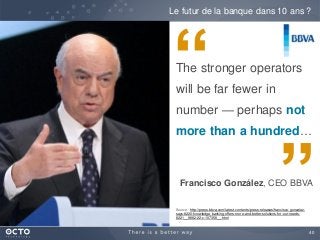
The stronger operators
will be far fewer in
number — perhaps not
more than a hundred…
Le futur de la banque dans 10 ans ?
“
”Source : http://press.bbva.com/latest-contents/press-releases/francisco-gonzalez-
says-8220-knowledge-banking-offers-more-and-better-solutions-for-our-needs-
8221__9882-22-c-107358__.html
Francisco González, CEO BBVA
41
Seulement 9% des entreprises « disruptées »
survivent.
Mais 100% des 9% d’entreprises qui
survivent, sans exception, ont mis en place
un nouveau business ‘disruptant’ dans une
nouvelle entité totalement séparée de la
maison mère.
Source : Colin Morrison, Huffingtonpost, Harvard Professor Shows Traditional Media
How to Cope With the Future, 28/06/2013
La statistique qui “tue”
“
”
42
Les disrupteurs disruptés
43
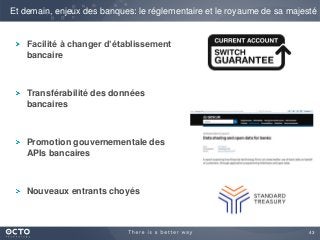
Facilité à changer d’établissement
bancaire
Transférabilité des données
bancaires
Promotion gouvernementale des
APIs bancaires
Nouveaux entrants choyés
Et demain, enjeux des banques: le réglementaire et le royaume de sa majesté
44
La bonne nouvelle
45
Source:http://www.keepcalm-o-matic.co.uk/p/keep-calm-and-thank-you-for-your-attention/
46
Table-Ronde – FinTech
Anne Laure Naveos
Crédit Mutuel Arkea
Jean-Michel Pailhon
Expert FinTech
Nicolas Guillaume
FriendsClear, PretPME,
Chappuis Halder
Patrice Bernard
Conix, C’est pas mon idée
Benoît Bazzocchi
SmartAngels
#FinTechDay